

Payment fraud is accelerating. Criminals adapt their tactics in real time and exploit the gap between transaction speed and detection speed. For payments leaders, the question is no longer whether to adopt AI transaction monitoring but how to deploy it across every corridor you operate in.
This guide covers the full landscape of AI-driven transaction monitoring for real-time payment fraud detection. You will learn how these systems work, where they outperform rule-based approaches, and what to look for when building or selecting a monitoring solution that fits your scale.
Rapyd delivers built-in fraud protection and compliance monitoring across 100+ countries through Rapyd Protect, giving you AI-powered transaction screening at the infrastructure level.
Key Takeaways: AI Transaction Monitoring
- AI transaction monitoring scores each payment against behavioral baselines rather than static rules, reducing false positives significantly.
- Machine learning models detect new fraud patterns by learning from confirmed cases and adapting as criminal tactics change.
- Real-time scoring closes the exploitation window that batch-processed systems leave open for layered money movement.
- Rapyd Protect applies AI-powered fraud monitoring across 100+ countries with built-in 3DS authentication and customizable rules.
- Explainable AI outputs give compliance teams audit-ready documentation that regulators can review during examinations.
What Is AI Transaction Monitoring?
AI transaction monitoring is the process of analyzing payment activity using machine learning and behavioral analytics instead of static rule sets. Every transaction is scored against a customer-specific baseline that accounts for spending patterns, geography, device data, and counterparty history.
Traditional systems flag transactions that exceed fixed thresholds. An AI-based system asks a different question: does this specific transaction deviate from what this specific customer normally does?
The distinction matters. A $50,000 wire from a corporate account with regular transfer history carries a very different risk profile than the same amount from a retail customer who has never sent more than $500 internationally.
The result is fewer false alerts, faster detection of new fraud typologies, and a monitoring framework that adapts as criminal tactics evolve.
How Does AI Transaction Monitoring Differ From Rule-Based Systems?
Rule-based monitoring relies on predefined thresholds. If a wire transfer exceeds a set amount or originates from a flagged jurisdiction, the system triggers an alert. This approach catches known patterns, but criminals learn the thresholds and structure their transactions to stay below them.
AI-based systems build an individual behavioral profile for each customer, merchant, and counterparty. The model calculates a probability score on a sliding scale. Low scores get auto-dismissed. High scores route to senior analysts.
According to Visa’s transaction monitoring research, around 45% of merchants now face increased risk from irrevocable real-time payments, making behavioral scoring essential for managing fraud at speed.
Core Technologies Behind AI Transaction Monitoring
Supervised and Unsupervised Machine Learning
Supervised models train on labeled datasets of confirmed fraudulent and legitimate transactions. They learn the exact patterns that distinguish a suspicious activity report from normal behavior. Unsupervised models identify outliers without prior labeling, grouping similar transactions and flagging anything that falls outside established clusters.
Most production systems combine both approaches. Supervised learning handles known fraud typologies. Unsupervised learning catches the unknown patterns that no one has labeled yet.
Behavioral Profiling and Anomaly Detection
Behavioral profiling builds a statistical model of each customer’s normal transaction patterns, including amounts, counterparties, timing, and geographies. When a transaction deviates from that individual baseline, the system flags it for review.
Anomaly detection algorithms such as isolation forests, autoencoders, and clustering methods identify transactions that do not fit expected behavior. These techniques catch what static rules miss entirely: the patterns that look normal in isolation but are suspicious in context.
Network Analysis for Layered Fraud Detection
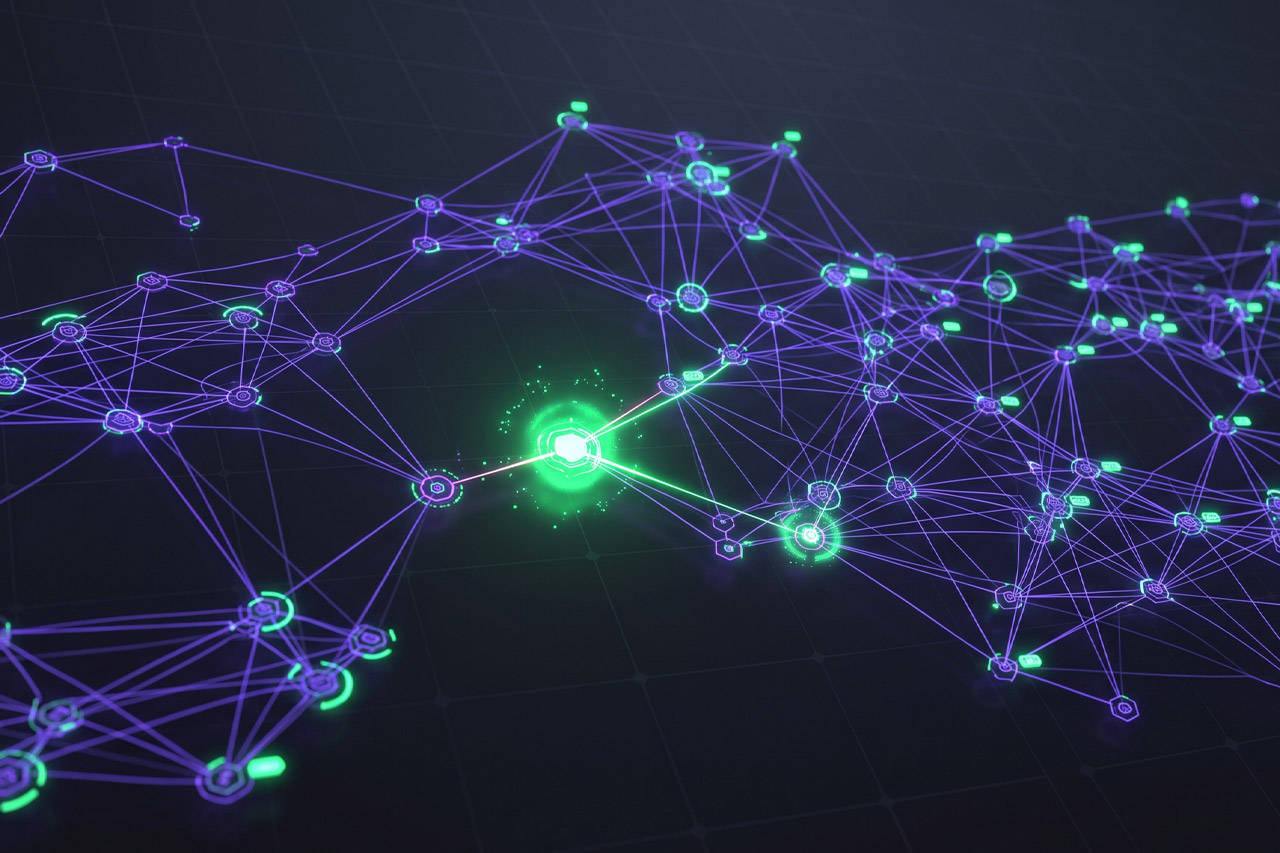
Network analysis maps relationships between accounts to detect layering patterns where money passes through multiple entities in rapid succession. A single transaction may look legitimate, but the network graph reveals that the same funds have moved through five accounts in under an hour.
This capability is critical for cross-border payouts where funds traverse multiple corridors and jurisdictions before reaching their final destination.
Predictive Risk Scoring
Predictive scoring assigns a probability value to each transaction before it clears. Rather than a binary alert or no-alert outcome, the system outputs a score from 0 to 100. Your compliance team sets the thresholds for auto-dismissal, junior review, senior review, and automatic escalation.
This approach means senior analysts spend their time on genuinely suspicious activity instead of closing thousands of alerts that were never risky.
Why Real-Time Monitoring Matters for Payment Fraud Detection
Batch processing was acceptable when transactions cleared overnight. Real-time payments settle in under three seconds and are often irrevocable. A money mule network can complete an entire layering cycle in minutes if your monitoring system only runs in hourly or daily batches.
Real-time AI transaction monitoring evaluates each payment before it clears, typically scoring it in under 200 milliseconds. This closes the exploitation window that batch systems leave open and allows you to hold suspicious transfers mid-sequence while investigation proceeds.
For businesses processing payments across 190+ countries, the stakes are high. Rapyd’s infrastructure handles global payment processing with built-in monitoring that operates at transaction speed, not batch speed.
How AI Reduces False Positives in Transaction Monitoring
False positives are the single largest operational cost in traditional transaction monitoring. Industry benchmarks show false positive rates between 95% and 99% for rule-based AML systems. That means for every 100 alerts, only 1 to 5 represent genuine suspicious activity.
AI reduces this burden through three mechanisms. Behavioral baselines compare each transaction against what that specific customer normally does, not a universal threshold. Ensemble models combine multiple algorithms and take a weighted vote, reducing noise.
Risk scoring replaces binary alerting. Low-probability alerts get auto-dismissed with documented reasoning, freeing analysts to focus on genuinely suspicious activity.
The downstream effect extends to Suspicious Activity Report (SAR) filing. When the AI system has already scored a transaction, analyzed the counterparty network, and documented its reasoning, the SAR narrative pre-populates itself. Analysts can redirect time from documentation to actual investigation.
Explainable AI and Regulatory Compliance
One common concern is whether regulators will accept AI-driven decisions. The answer from bodies like FinCEN and EU AML supervisors is clear: they do not require simple models. They require auditable reasoning.
Explainable AI (XAI) techniques such as SHAP (SHapley Additive exPlanations) values produce plain-language explanations for each risk score. A sample output might read: “This transaction scored 82/100 because the receiving account received 14 transactions from high-risk jurisdictions in the past 30 days, and the sending account has no prior international transfer history.”
That level of specificity is more defensible in a regulatory examination than a simple rule trigger. It gives your compliance team a documented decision trail that auditors can trace backward.
How to Build an AI Transaction Monitoring System
Step 1: Assess Your Current Monitoring Architecture
Start by mapping your existing rule engine, data pipelines, and alert workflows. Identify the false positive rate, average alert resolution time, and the percentage of analyst hours spent on alerts that yield no action. These metrics become your baseline for measuring AI performance.
Step 2: Prepare Your Transaction Data
Effective AI models require 12 to 24 months of historical transaction data, including labeled examples of confirmed fraud and legitimate activity. Data quality directly impacts model performance. Inconsistent, incomplete, or outdated records will produce inaccurate scoring.
Step 3: Select Your Model Architecture
Choose between a standalone AI system or a hybrid approach that layers machine learning on top of your existing rules. Most organizations start with the hybrid model, keeping rules for known regulatory thresholds while adding AI for behavioral detection and anomaly scoring.
Step 4: Deploy Real-Time Scoring Infrastructure
Your scoring system needs sub-200-millisecond latency end to end. This requires streaming data pipelines (tools like Apache Kafka or AWS Kinesis), in-memory feature stores for pre-computed behavioral features, and fallback rule engines for transaction types the model has not yet encountered.
Step 5: Establish Model Governance and Retraining
Set a defined retraining cadence, document your model validation process, and assign clear ownership for approving changes. Regulators expect to see model risk management documentation during examinations. Without governance, even a high-performing model becomes a regulatory liability.
Step 6: Integrate With Your Payment Platform
Your monitoring system needs to function as a low-latency microservice that plugs into your existing API-based payment flows. A platform built for overnight batch processing cannot be retrofitted for real-time scoring without a fundamental architectural rebuild.
AI Transaction Monitoring for Cross-Border Payments
Cross-border payments add jurisdictional complexity to every monitoring decision. A transaction that meets US Bank Secrecy Act requirements may need additional documentation under EU AML directives. What counts as a high-risk jurisdiction differs between FATF member countries.
AI-based platforms address this through jurisdiction-aware rule overlays that sit on top of the core machine learning scoring engine. The ML model scores the base risk. The rule overlay then checks the transaction against destination-specific reporting obligations and flags where requirements differ by country.
If you operate across ten or more markets, running manual AML compliance against ten different regulatory frameworks simultaneously is not realistic at scale. Rapyd, as a directly licensed Visa and Mastercard acquirer in the UK, EU, and Singapore, operates card acquiring with in-depth compliance expertise across multiple regulatory frameworks.
Common Challenges When Deploying AI Transaction Monitoring
Data Quality and Integration
AI models are only as accurate as the data they train on. Merging data from legacy banking platforms alongside modern fintech applications introduces inconsistencies. Invest in data normalization and validation before model training, not after.
Balancing Explainability With Sophistication
Complex deep learning models can outperform simpler approaches, but they risk becoming opaque. Hybrid architectures that combine ML scoring with rule-based logic for transparency give you the accuracy of advanced models with the explainability regulators require.
Cost and Resource Planning
Building, maintaining, and scaling AI-based monitoring involves upfront investment in technology, talent, and process redesign. Weigh the cost of reduced false positives and faster detection against ongoing licensing, retraining, and infrastructure expenses. For many organizations, platforms with built-in fraud monitoring reduce this overhead significantly.
How to Evaluate an AI Transaction Monitoring Vendor
Not every vendor delivers the same results. Focus your evaluation on these criteria before committing to a platform.
First, ask for documented false positive reduction benchmarks from live deployments at institutions with a similar transaction mix and volume. Not projected reductions. Actual production numbers.
Second, evaluate explainability output quality. Can the system’s reasoning attach directly to SAR filings? Can a compliance officer without a data science background use the explanations confidently during an examination?
Third, test real-time scoring latency. What is the average and 99th-percentile scoring time under peak transaction load? What happens if the ML service goes offline?
Fourth, review model governance documentation. How often are models retrained? Who approves changes? Is there a documented validation process that meets regulatory model risk management requirements?
Finally, confirm jurisdiction coverage. Which regulatory frameworks are included as standard? How quickly can new markets be added? Rapyd’s network covers 190+ countries and 150+ currencies, with Rapyd Protect delivering AI-powered fraud monitoring, 3DS authentication, and a customizable rules engine across every market.
The Role of 3D Secure in AI Transaction Monitoring
3D Secure (3DS) authentication adds an identity verification layer during card-not-present transactions. When integrated with AI transaction monitoring, 3DS becomes a precision tool rather than a blunt instrument.
AI scores each transaction and triggers 3DS only when the risk score exceeds your defined threshold. Low-risk transactions from known customers pass through without additional authentication, keeping your checkout conversion rates high while blocking suspicious activity.
Rapyd Protect includes built-in 3DS authentication that you can configure at the rule level. You decide which transactions trigger the additional verification step, giving your team full control over the balance between security and customer experience.
AI Transaction Monitoring for Chargebacks and Disputes
Transaction monitoring does not end at the point of sale. Post-transaction surveillance tracks disputes, chargebacks, and refund patterns to identify fraudulent returns and organized chargeback fraud schemes.
AI models trained on dispute data can flag high-risk refund requests before they clear and identify merchants with abnormal dispute ratios. They also detect first-party fraud, where the cardholder disputes a legitimate purchase.
Post-transaction monitoring connects to your overall fraud prevention strategy by feeding dispute outcomes back into the model as training data.
The Future of AI in Payment Fraud Detection
The next evolution in AI transaction monitoring is the move from scoring to autonomous investigation. Agentic AI systems can independently investigate and close low-risk alerts, pre-populate SAR narratives, and route only genuinely complex cases to human analysts.
Foundation models trained on payment data (Visa, for example, has published research on transformer-based models built specifically for transaction understanding) are expected to further improve detection accuracy by understanding the full context of a payment journey, not just individual data points.
For payments leaders, the strategic direction is clear: invest in monitoring infrastructure that learns, adapts, and operates at the speed your payment flows demand. Platforms like Rapyd, which embed fraud protection across hundreds of payment methods and 100+ countries, give you that infrastructure from day one.
In Conclusion: Building a Transaction Monitoring Strategy That Scales
AI transaction monitoring replaces the static, rule-based approach that generates overwhelming false positive volumes with a system that scores risk contextually, adapts to new threats, and gives your compliance team audit-ready documentation.
The components are clear: behavioral profiling, real-time scoring, explainable AI outputs, and jurisdiction-aware compliance overlays. The operational benefits are measurable: fewer false positives, faster detection, lower analyst burnout, and stronger regulatory standing.
Your path forward starts with assessing your current monitoring architecture and quantifying your false positive costs. Evaluate platforms that deliver real-time AI scoring at global scale.
Rapyd’s infrastructure gives you built-in fraud protection, direct acquiring licenses, and compliance monitoring across 190+ countries, so you can focus on growth instead of manual alert review.
Subscribe Via Email
Thank You!
You’ve Been Subscribed.